Tribunal denies fishy business property relief claim
The First-tier Tribunal (FTT) has disallowed a claim for business property relief (BPR), despite the business in question being a long-established fishery. What went wrong?
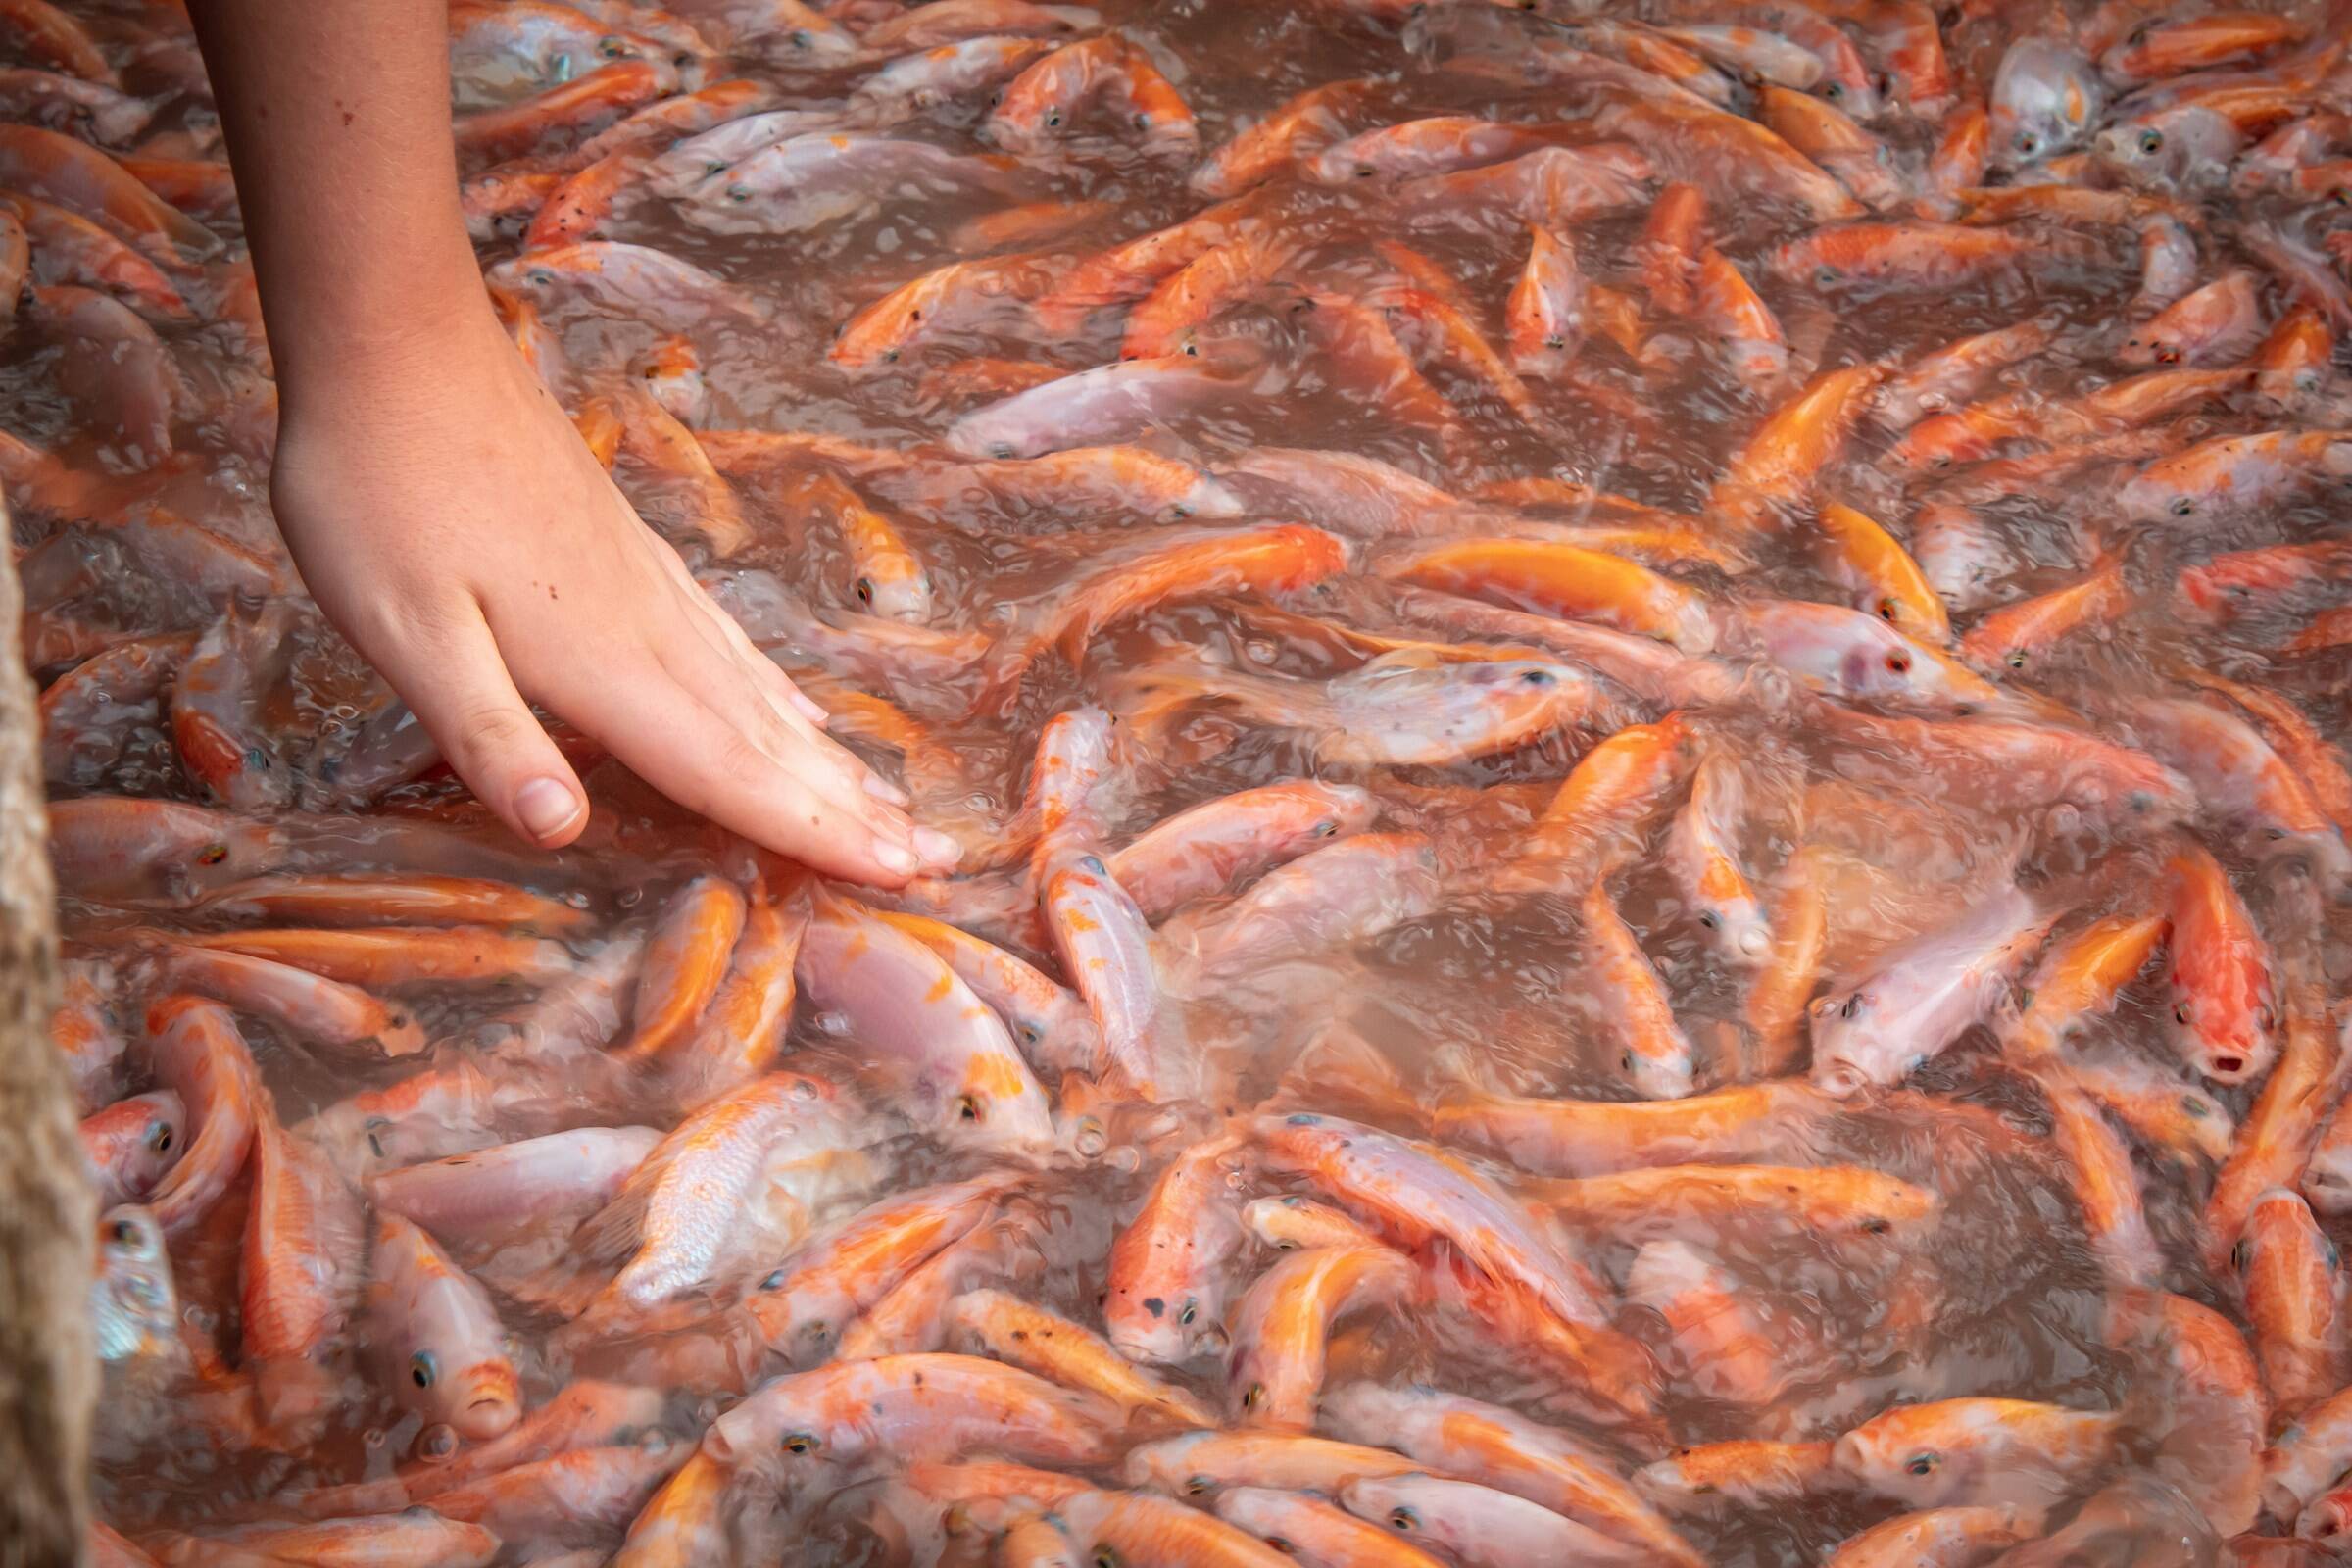
Mrs Pearce (Mrs P) had carried on a fishery business for 17 years, having taken over when her husband died. Mr P had built a profitable stocked fishery business, which involved purchasing fish and stocking his part of the river for members to catch. Each fisherman was allowed to take two fish home. However, shortly after Mrs P took over, the Environment Agency became aware of the impact of stocked fisheries on the native fish and refused to renew fish stocking licences.
The nature of the business therefore changed from being a stocked fishery to the maintaining of a wild fishery. Due to the conservation efforts, members could not use certain hooks and were required to return all fish to the river. The business’ income declined as a result of the changes and made very minimal profits. Members had the use of an outside toilet and car park. Mrs P’s activities included maintaining the land, taking and managing bookings and greeting customers with a drink.
However, the tribunal found that the non-investment activities were not of sufficient significance to tip the balance of the business overall from an investment business to a non-investment business. It was noted that had the business provided services such as tuition in fishing, ghillies to guide the rods, if it had sold or hired equipment or provided catering or a bar the outcome might have been different. In this case, the business had become one of mainly holding land as an investment, by collecting fees from fishermen and maintaining the land. This case highlights the need to regularly review business activities as, despite the taxpayer working very hard in a long established business, the change in responsibilities meant that valuable business relief was not available.
Related Topics
-
Will new property tax rates erode tax efficiency?
You recently purchased a new trading premises for your business and plan to charge your company rent. As tax rates on property income are going up in April 2027, is this arrangement likely to be tax efficient?
-
MTD taxpayers warned to check two accounts for tax bills
Taxpayers who joined Making Tax Digital (MTD) for Income Tax in April 2026 are being warned that their tax payment information may be split between two separate HMRC accounts. With the January Self Assessment deadline approaching, could you be overlooking part of your tax bill?
-
Extra reporting requirements for close companies scrapped
Government plans for rigorous reporting of transactions between close companies and their participators have been binned. What's changed?